You can learn how to check business credit by purchasing reports directly from major bureaus or using a unified monitoring platform. Commercial credit files are public records and do not require your consent for third parties to access. It is often frustrating for new owners to find that business reports carry a cost while personal reports are free. Many new LLCs discover their files are empty because they have not yet established trade history.
You can begin generating reportable data by purchasing essentials from a net 30 office supplies vendor, a net 30 apparel vendor, or a net 30 tech and electronics vendor. This article explains how to monitor your standing and build a profile using an EIN only with no personal guarantee. We will outline the specific workflow of applying, ordering, and paying to ensure your activity is reported monthly to Equifax Business, Creditsafe, and FairFigure. Results vary. There are no guaranteed outcomes or specific score boosts, and this content is not financial or legal advice.
Key Takeaways
- Identify the specific bureaus where you can learn how to check business credit and monitor your commercial standing.
- Understand the process of opening a Net 30 office supplies vendor account using an EIN with no personal guarantee required.
- Learn why monthly reporting to Equifax Business, Creditsafe, and FairFigure is necessary for building a visible trade profile.
- Discover how a $60 minimum order and a $5,500 credit line allow you to secure essential products while establishing history.
- Acknowledge that results vary and no specific score boost is guaranteed from following these credit-building steps.
Why You Must Check Business Credit Scores Regularly
Regular monitoring is the only way to verify your company is represented accurately to lenders. Most business credit reports contain demographic data that can be outdated or incorrect. If your legal address or business name is wrong, it can prevent you from getting approved for a net 30 apparel vendor account. Checking your scores monthly helps you spot these errors before they cause a denial. It also helps you identify identity theft early. If a person opens an account using your EIN, you will see it on your report. Early detection allows you to dispute the activity with the bureau. This prevents long-term damage to your corporate standing. Results vary, and checking your score does not guarantee a specific increase. This content is not financial or legal advice.
The Difference Between Personal and Business Credit
Personal credit tracks your individual spending using a Social Security Number. Business credit tracks your entity using an EIN. Since business credit is public, competitors or partners can view your profile at any time. Maintaining a separate profile keeps your personal credit score isolated from your company’s financial obligations. It allows you to build a reputation for the business as its own financial person. You don’t have to risk your personal assets to buy supplies. This separation is a standard practice for professional LLCs. Knowing how to check business credit allows you to maintain this boundary between your private and commercial finances.
Benefits of a High Business Credit Score
A strong score leads to better trade credit arrangements. You can secure inventory without a personal guarantee. This lowers your financial risk as a business owner. High scores also qualify you for credit lines up to $5,500. This is useful for purchasing office supplies or electronics through a net 30 office supplies vendor. Establishing credit with an A+ BBB rated company that has been in business for 6+ years ensures your history is handled by an experienced vendor. Better scores can also lead to lower insurance premiums. Landlords may check your business credit before offering a lease for office space. A high score shows you are a reliable tenant. This can result in a lower security deposit or more flexible payment schedules.
Experian Small Business focuses primarily on risk management for lenders. Based on publicly available information, they prioritize providing data for loan approvals. However, they may not explain how a business owner uses these scores to negotiate better terms with specific suppliers. Competitor terms are drawn from publicly published reviews and are accurate to the best of our knowledge at time of writing. Confirm current terms directly with any vendor.
Business Credit Bureaus and Your Net 30 Account
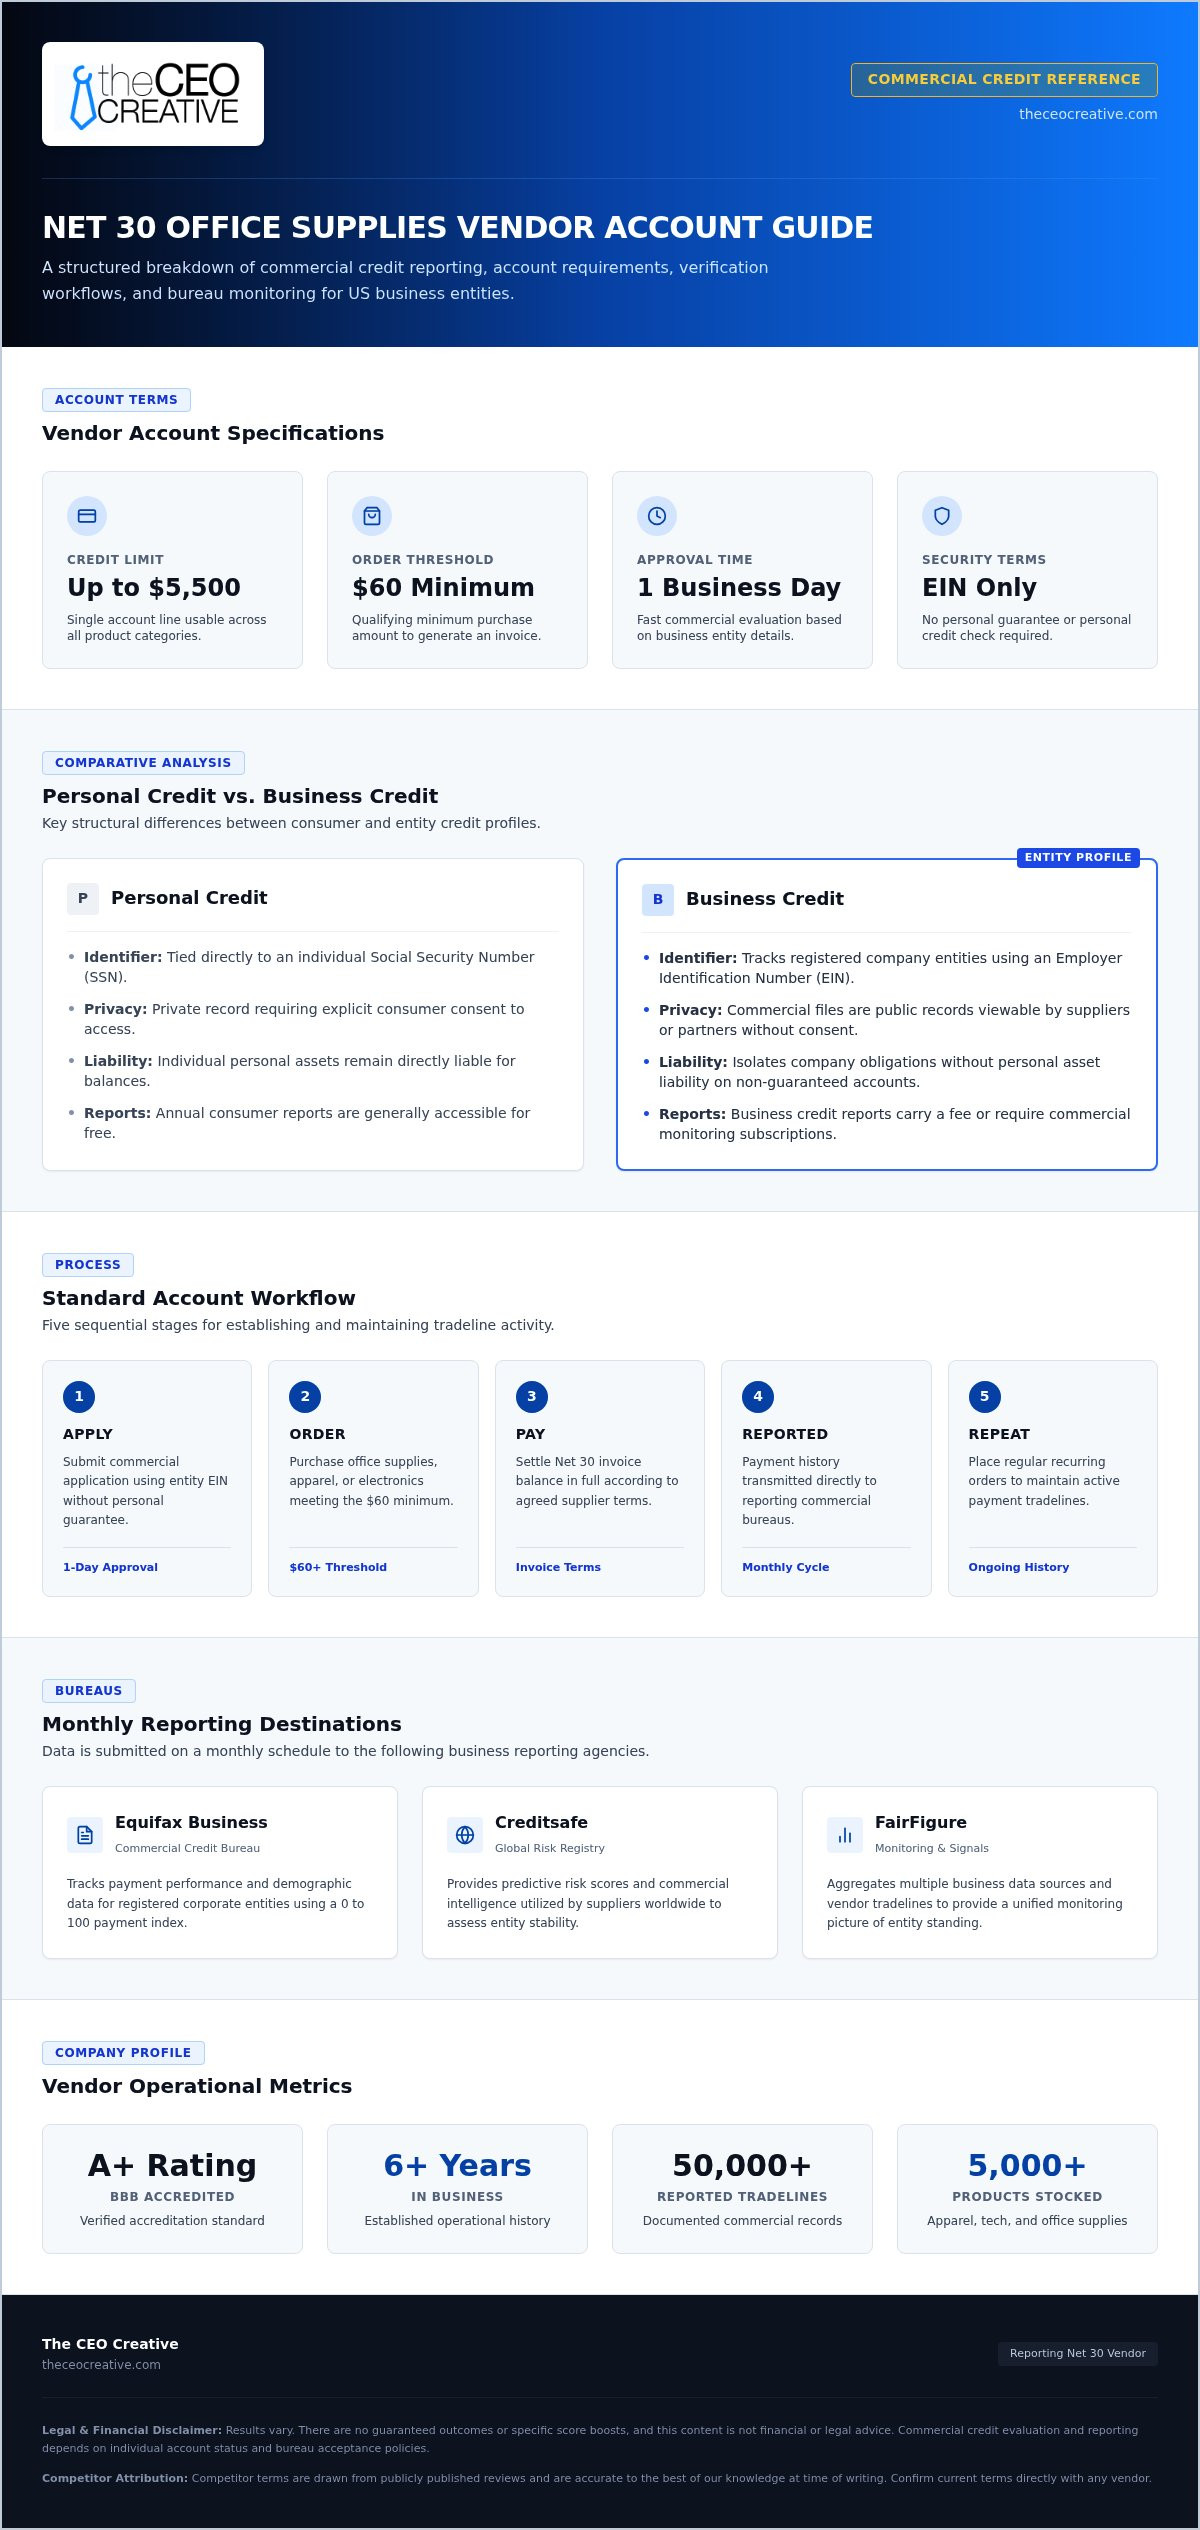
Business credit data is collected by several major reporting agencies. When you research how to check business credit, you will find that different vendors report to different bureaus. A net 30 office supplies vendor typically reports to specialized agencies rather than consumer bureaus. This reporting is done monthly to ensure your tradeline stays current. The CEO Creative reports your payment data to Equifax Business, Creditsafe, and FairFigure.
Equifax Business and Creditsafe
Equifax Business tracks credit, payment, and demographic data specifically for LLCs and corporations. It evaluates how your business handles its financial obligations over time. This bureau uses a 0 to 100 scale for its payment index. Creditsafe is a global bureau used by many suppliers to check vendor risk before approving terms. It provides a risk score that predicts the likelihood of a business failing. Consistent monthly reporting to these bureaus builds a reliable payment history. If you’re starting a new business, these reports are often the first place lenders look. You can find more information on managing these relationships in this SBA guide to Net 30 vendor accounts. Maintaining high scores across these bureaus requires paying invoices on time every month.
FairFigure and Alternative Data
FairFigure provides a combined view of various business credit signals. It acts as a monitoring platform that aggregates data from multiple sources to give a broader picture of your company’s health. Alternative data includes utility payments and specific vendor tradelines that might not appear on traditional reports. Building these scores requires active accounts with reporting vendors. You don’t need a personal credit check or a personal guarantee to begin this process. Applying for an EIN only net 30 account allows you to start generating this data immediately.
When you learn how to check business credit, you’ll see that having diverse data points is beneficial. Some bureaus focus on industry-specific risk, while others look at general payment trends. The CEO Creative provides a $5,500 credit line with a $60 minimum order. This helps you stock 5,000+ products while establishing a footprint with Equifax Business, Creditsafe, and FairFigure. Approval typically occurs within one business day based on your EIN. Results vary. There are no guaranteed outcomes or specific score boosts. This content is not financial or legal advice.
How to Check Business Credit Reports From Major Agencies
To access your file, visit the official portal of a commercial bureau like Equifax Business or Creditsafe. You will enter your company name and state to locate your specific file. If no file exists, the system will notify you that a record has not yet been established. You can then purchase a one-time report or a monthly monitoring subscription. This is the standard method for how to check business credit when you need to see the specific data points lenders review. Focus your review on the “Trade Lines” or “Payment History” section. This area lists individual accounts and their current payment status.
The Business Credit Building Workflow
Establishing a new file requires a consistent cycle of activity. You can follow this specific process for establishing and monitoring business credit effectively.
- Apply: Submit an online application using your EIN for 1-day approval.
- Order: Place an order for at least $60 to trigger the reporting process.
- Pay: Settle the invoice in full within the Net 30 day terms.
- Reported: The vendor updates Equifax Business, Creditsafe, and FairFigure during the monthly reporting cycle.
- Repeat: Place a new order every few months to keep the tradeline active and visible.
What to Look for in a Credit Report
Check that your business address matches your Secretary of State filing exactly. Inconsistent addresses can create split files where your credit history is divided across two different records. Verify that your $5,500 credit line is visible under the tradeline section of your report. If you find a late payment that you actually paid on time, you must contact the bureau to start a dispute. Knowing how to check business credit helps you catch these errors before they impact your ability to get terms from a net 30 office supplies vendor. Results vary, and there are no guaranteed outcomes or specific score boosts. This content is not financial or legal advice.
Mistakes to Avoid With a Net 30 Business Account
Managing a net 30 office supplies vendor account requires strict adherence to specific terms. Many new business owners assume that every purchase automatically builds their commercial score. This is not always the case. You must understand how to check business credit to verify that your activity is being recorded correctly. One common error is assuming a vendor reports to every bureau. The CEO Creative reports to Equifax Business, Creditsafe, and FairFigure monthly. If you are looking for reporting to other agencies, you will not find it here. Results vary, and there are no guaranteed outcomes for your score.
Another mistake is failing to meet the $60 minimum order requirement. If your order falls below this amount, the tradeline may not report for that month. You should also avoid applying for too many accounts in a short window. While an EIN only net 30 account involves no personal credit check, some vendors may perform hard inquiries that can lower your score. Spreading your applications out helps maintain a stable profile while you establish your initial history.
Reporting and Payment Errors
Paying after the 30-day due date is a significant risk to your business standing. Even a payment made 31 days after the invoice date can result in negative reporting to Equifax Business. This can lower your payment index score and signal risk to other potential suppliers. You should also avoid letting your account go dormant. Not using the account for six months or longer may cause the tradeline to stop appearing on your active reports. Always verify that the vendor has your correct EIN on file. An incorrect number means your payment data will never reach your business profile, wasting your efforts to build history.
Inaccurate Business Information
Consistency in your public records is vital for a clear credit profile. Using a personal home address instead of a registered business address can cause data mismatches. Bureaus often create a split file if they cannot verify your physical location against official records. This makes it difficult when you learn how to check business credit because your payment data is fragmented across different entries. Ensure your business name is exactly the same on every vendor application. If you use the suffix LLC on one account and omit it on another, the bureau systems may not link the tradelines to the same entity. Finally, ensure your business is in good standing with the Secretary of State. Vendors and bureaus routinely check this status during their monthly updates. If your business is listed as inactive, your reporting may be suspended.
Establishing Credit With a Net 30 Office Supplies Vendor
A net 30 office supplies vendor serves as a primary tool for new LLCs starting from zero. While knowing how to check business credit is essential, you must first have data to monitor. The CEO Creative provides a path to establish this history by reporting your monthly payment activity. You can access a credit line up to $5,500 to purchase items that support your daily operations. This account helps build a corporate identity that’s separate from your personal finances. We’ve been in business for 6+ years and have reported over 50,000 tradelines for our clients. Results vary. There are no guaranteed outcomes or specific score boosts, and this content isn’t financial or legal advice.
Available Products for Your Business
You can use your credit line to stock up on a variety of items. The catalog includes over 5,000 products ranging from basic stationery to custom branded goods. You might order custom t-shirts and apparel to create a professional look for your team. You can also purchase custom notebooks and stationery for your daily operations. The store offers tech and electronics through a dedicated Net 30 account, allowing you to upgrade your office equipment without immediate cash outlay. Every purchase of $60 or more qualifies for reporting. This activity creates the tradelines you see when you learn how to check business credit.
Applying Without a Personal Guarantee
Most traditional lenders require a personal credit check and a personal guarantee. This links your personal assets to your business debt. The CEO Creative uses a different model. Approval is based on your EIN and business information only. You don’t need to provide a Social Security number for a credit check to open a membership account. This structure lowers the financial risk for the business owner. The application process is efficient. Most US-based businesses receive approval within one business day. You can read more about how to build business credit without a loan to understand this strategy better.
Once you’re approved, you simply place your order and pay the invoice within 30 days. We report this information monthly to Equifax Business, Creditsafe, and FairFigure. Consistent use of the account demonstrates to other creditors that your business can handle trade credit responsibly. We don’t report to Dun & Bradstreet or Experian. Maintaining an active account shows lenders that your business is operational and maintains steady cash flow.
Start Building Your Commercial History
Establishing a strong credit profile is a strategic step for any new LLC. You now understand the steps for how to check business credit and why monitoring your Equifax Business and Creditsafe reports is necessary. Maintaining a high payment index requires consistent activity and on-time payments. By using a Net 30 office supplies vendor, you generate the data that lenders look for when reviewing your company. We provide monthly reporting to Equifax Business, Creditsafe, and FairFigure to ensure your profile stays current. Our A+ BBB rating reflects our commitment to providing reliable service to growing organizations. You can access a credit line up to $5,500 with no personal guarantee required. Results vary. There are no guaranteed outcomes or specific score boosts, and this content is not financial or legal advice.
Take the next step in your professional development. We look forward to supporting your business as you build a sustainable financial foundation.
Frequently Asked Questions
How long does it take for a Net 30 vendor to report to bureaus?
Reporting occurs once a month on a batch schedule. It doesn’t happen instantly after you pay your invoice. Most vendors send their data to agencies like Equifax Business at the end of a reporting cycle. After the vendor reports, it can take the bureau several weeks to process the data and update your profile. You should monitor your reports monthly to see when new tradelines appear on your history.
Can I check my business credit score for free?
You can use monitoring platforms like FairFigure to view basic business credit data for free. However, most major bureaus like Equifax Business and Creditsafe charge a fee for a comprehensive report. Learning how to check business credit often involves a mix of free summaries and paid, detailed pulls. There is no federal law requiring commercial bureaus to provide free annual business credit reports to company owners.
Do Net 30 vendors report to Dun & Bradstreet?
Some vendors report to Dun & Bradstreet, but many specialized suppliers do not. The CEO Creative reports strictly to Equifax Business, Creditsafe, and FairFigure. We don’t report to Dun & Bradstreet or Experian. When you choose a Net 30 office supplies vendor, you must verify their specific reporting partners. This ensures your payment data reaches the bureaus you’re targeting to build your specific commercial credit profile.
What is the minimum order for a reporting tradeline?
The minimum order to qualify for monthly tradeline reporting at The CEO Creative is $60. Orders below this threshold won’t be sent to the credit bureaus. This requirement ensures that your business is making meaningful commercial purchases. You can meet this minimum by ordering custom apparel, tech electronics, or branded stationery. Consistent orders above this amount help keep your tradeline active and visible to future lenders.
Do I need a personal guarantee to check or build business credit?
You don’t need a personal guarantee to build business credit with our Net 30 vendor accounts. We approve applications based on your EIN and business information only. This protects your personal credit score from being affected by business debt. Most commercial credit bureaus allow you to check any business’s credit report by paying a fee. This process never requires a personal guarantee or a Social Security number to access the data.
Which bureaus does The CEO Creative report to?
The CEO Creative reports your payment history monthly to Equifax Business, Creditsafe, and FairFigure. We’ve successfully reported over 50,000 tradelines for our clients over the last 6+ years. We don’t report to Experian or Dun & Bradstreet. This specific reporting mix helps you establish a footprint with both traditional agencies and modern monitoring platforms. These bureaus are frequently used by B2B suppliers to evaluate your company’s creditworthiness.
How does a Net 30 account help my business credit score?
A Net 30 account helps your score by providing a verified record of your payment behavior. When you learn how to check business credit, you’ll see these accounts listed as tradelines on your report. Paying your invoices on time or early demonstrates reliability to future creditors. This data builds your payment index and risk scores over time. Results vary, and there are no guaranteed outcomes or specific score increases.
What happens if I pay my Net 30 invoice late?
Paying a Net 30 invoice late can result in negative reporting to Equifax Business and other bureaus. Even a small delay can lower your payment index and signal risk to other vendors. Most bureaus track days beyond terms to measure your delinquency risk. A high delinquency score makes it difficult to secure higher credit lines up to $5,500 or better terms with other suppliers. Always clear your balance within 30 days.